Author: Wayne Loke

  • New Zealand is Not a Fishbowl

    New Zealand is Not a Fishbowl

    In 1997 I was working at ABN AMRO in Kuala Lumpur, close enough to the Treasury floor to see what it was doing, and that was when my phone started ringing. Friends I hadn’t heard from in months wanted to know what was happening, because someone at a foreign bank must surely know, and I guess they hoped I’d tell them it would all be over by the weekend. It wasn’t. Thailand had floated the baht in July and it collapsed, and within weeks the ringgit was being traded hard by speculators, sliding from around 2.50 to the US dollar to past 4.50 by January 1998. The stock market lost more than half its value by the end of 1997, and kept falling through 1998. My own savings and investments went down with everything else, and there wasn’t much I could do about it except watch.

    Around me, people sold at whatever price they could get, to cut their losses. I held on, mostly because I couldn’t see what selling at the bottom would fix, and once things rebounded that turned out to be the right call. I didn’t follow the crowd, and I’ve been glad of it ever since. This is not financial advice, but this is what I did.

    The government had its own explanation. George Soros and the currency speculators were blamed, loudly and often, and for a while that was the story everyone repeated. Then in September 1998 the prime minister imposed capital controls and pegged the ringgit at 3.80 to the dollar; overnight, a floating currency became a fixed one, and money that wanted to leave the country couldn’t. The economy shrank in 1998, Malaysia’s first recession in many years, and measured in US dollars it didn’t get back to its 1996 size until 2003. Indonesia had riots. South Korea, Thailand, Hong Kong, Singapore and Japan all took damage, and ordinary people across the region lost money and livelihoods for reasons nobody explained to them in a way they could follow.

    Inside the bank, I saw the other side of it. Our Treasury team made the bank’s annual profit target within a week, and kept going, though senior leadership kept that quiet given how sensitive things were. I’ve told that story before, in What AI Exposes. In a crisis there are losers and there are winners, and sometimes they’re in the same building.

    What stayed with me was how little of it had started in Malaysia. A devaluation in Bangkok ended up in my savings in Kuala Lumpur, and the explanation offered at home was one man’s name.

    Where the loops came from

    A couple of years later, one of the required readings on my MBA was Peter Senge’s The Fifth Discipline. It introduced me to systems thinking, and I’ve been hooked ever since, because it gave me words for what I’d just lived through.

    Senge’s building blocks are simple enough for a 12-year-old. A reinforcing loop is a chain where more causes more: the currency falls, people sell to protect themselves, the selling pushes the currency down further, and so more people sell. A balancing loop is something that pushes back: prices rise, people buy less, and the rise slows. Most of what happens in an economy is a handful of these loops running at once, some gaining strength and some fading, and the archetypes are the patterns they keep forming, over and over, whatever the country and whatever the decade.

    Read 1997 that way and the capital controls were a balancing loop built by hand, a government forcing a stop on a reinforcing loop that nothing else would break. It had an intention, and it had consequences, some intended and some not. Soros, whatever his part in it, was one link in the chain. Blaming him was a convenient place to stop thinking.

    Since then it’s become a habit. When I hear a plan, I look for the loops it hasn’t accounted for, and that usually tells me whether it will work and who it will hurt on the way. Your mental model stretches further than the people around you once you start doing this, which isn’t always comfortable for them, or for me.

    The fishbowl

    Now I live in a small economy again. New Zealand is open to the world in every way that matters for money: we import our fuel, we borrow offshore, we sell milk powder at prices set in global auctions, and well over half of our government bonds have historically been held by foreign investors, who buy and sell them alongside their US Treasuries.

    And yet when I read economic commentary in New Zealand, and especially the comments underneath it, much of it is drawn inside the border, as if the country were a fishbowl and everything that mattered were in the water. The RBNZ gets the credit or the blame for interest rates. The government gets the credit or the blame for the debt. Readers line up behind one view and stay there, anchored, and every new article confirms what they already believed.

    I don’t think there’s a right or wrong opinion in this. Every opinion is built from someone’s lived experience, what they’ve observed, and their own biases, and none of us has lived everything. I fall into the same trap. I’ve caught myself arguing a point hard with someone who simply didn’t have the information I had, and in What I Kept and What I Only Thought I Valued I wrote down the question I’ve learned to ask instead: what is your lived experience that I have not lived, that makes you believe what you do? The answer tells me where the gaps are, theirs and mine, and whether to help fill them or let them be. It’s not easy to take on an alternative view of something you haven’t lived through, observed, learned or read about.

    1997 is my lived experience that most New Zealanders haven’t had. It’s why I get uneasy when an analysis stops at the border.

    Here’s what stopping at the border misses right now. The RBNZ steers the short end of the interest rate curve, and that matters, because most New Zealand mortgages fix for one or two years and price off short-term swap rates the Reserve Bank does influence. The long end is another matter. Forsyth Barr puts the correlation between New Zealand and US 10-year government bond yields at around 80% over the past 20 years. You can see it working this year: between 1 July and 13 October, New Zealand’s 10-year yield took about 70% of the rise in the US 10-year. That came in through the offshore bondholders, without anyone in Wellington deciding it, and it flows into the government’s borrowing costs and from there into every party’s debt track.

    Petrol shows the same thing at the pump. On 13 October, 91 octane averaged NZ$3.61 a litre, up nearly 14% in four weeks, on tanker attacks and supply fears half a world away and a New Zealand dollar sitting near the bottom of its two-year range. And there are costs the model doesn’t even try to hold: earthquakes, floods and extreme weather get priced into global reinsurance, and that comes back to us as higher premiums. Ignore them, exclude them, hide them, they still get imported into the economy as a whole.

    Follow the money, people say. Behind every flow of money there’s an intention, mostly greed or fear, and behind every intention a consequence nobody fully planned. We’re in the 21st century and human nature hasn’t moved much: everyone wants more resources and fears losing what they have. When a country prospers, its people get on with life. When it doesn’t, you get friction, and in 1997 I saw how quickly that turns ugly.

    Not a Fishbowl

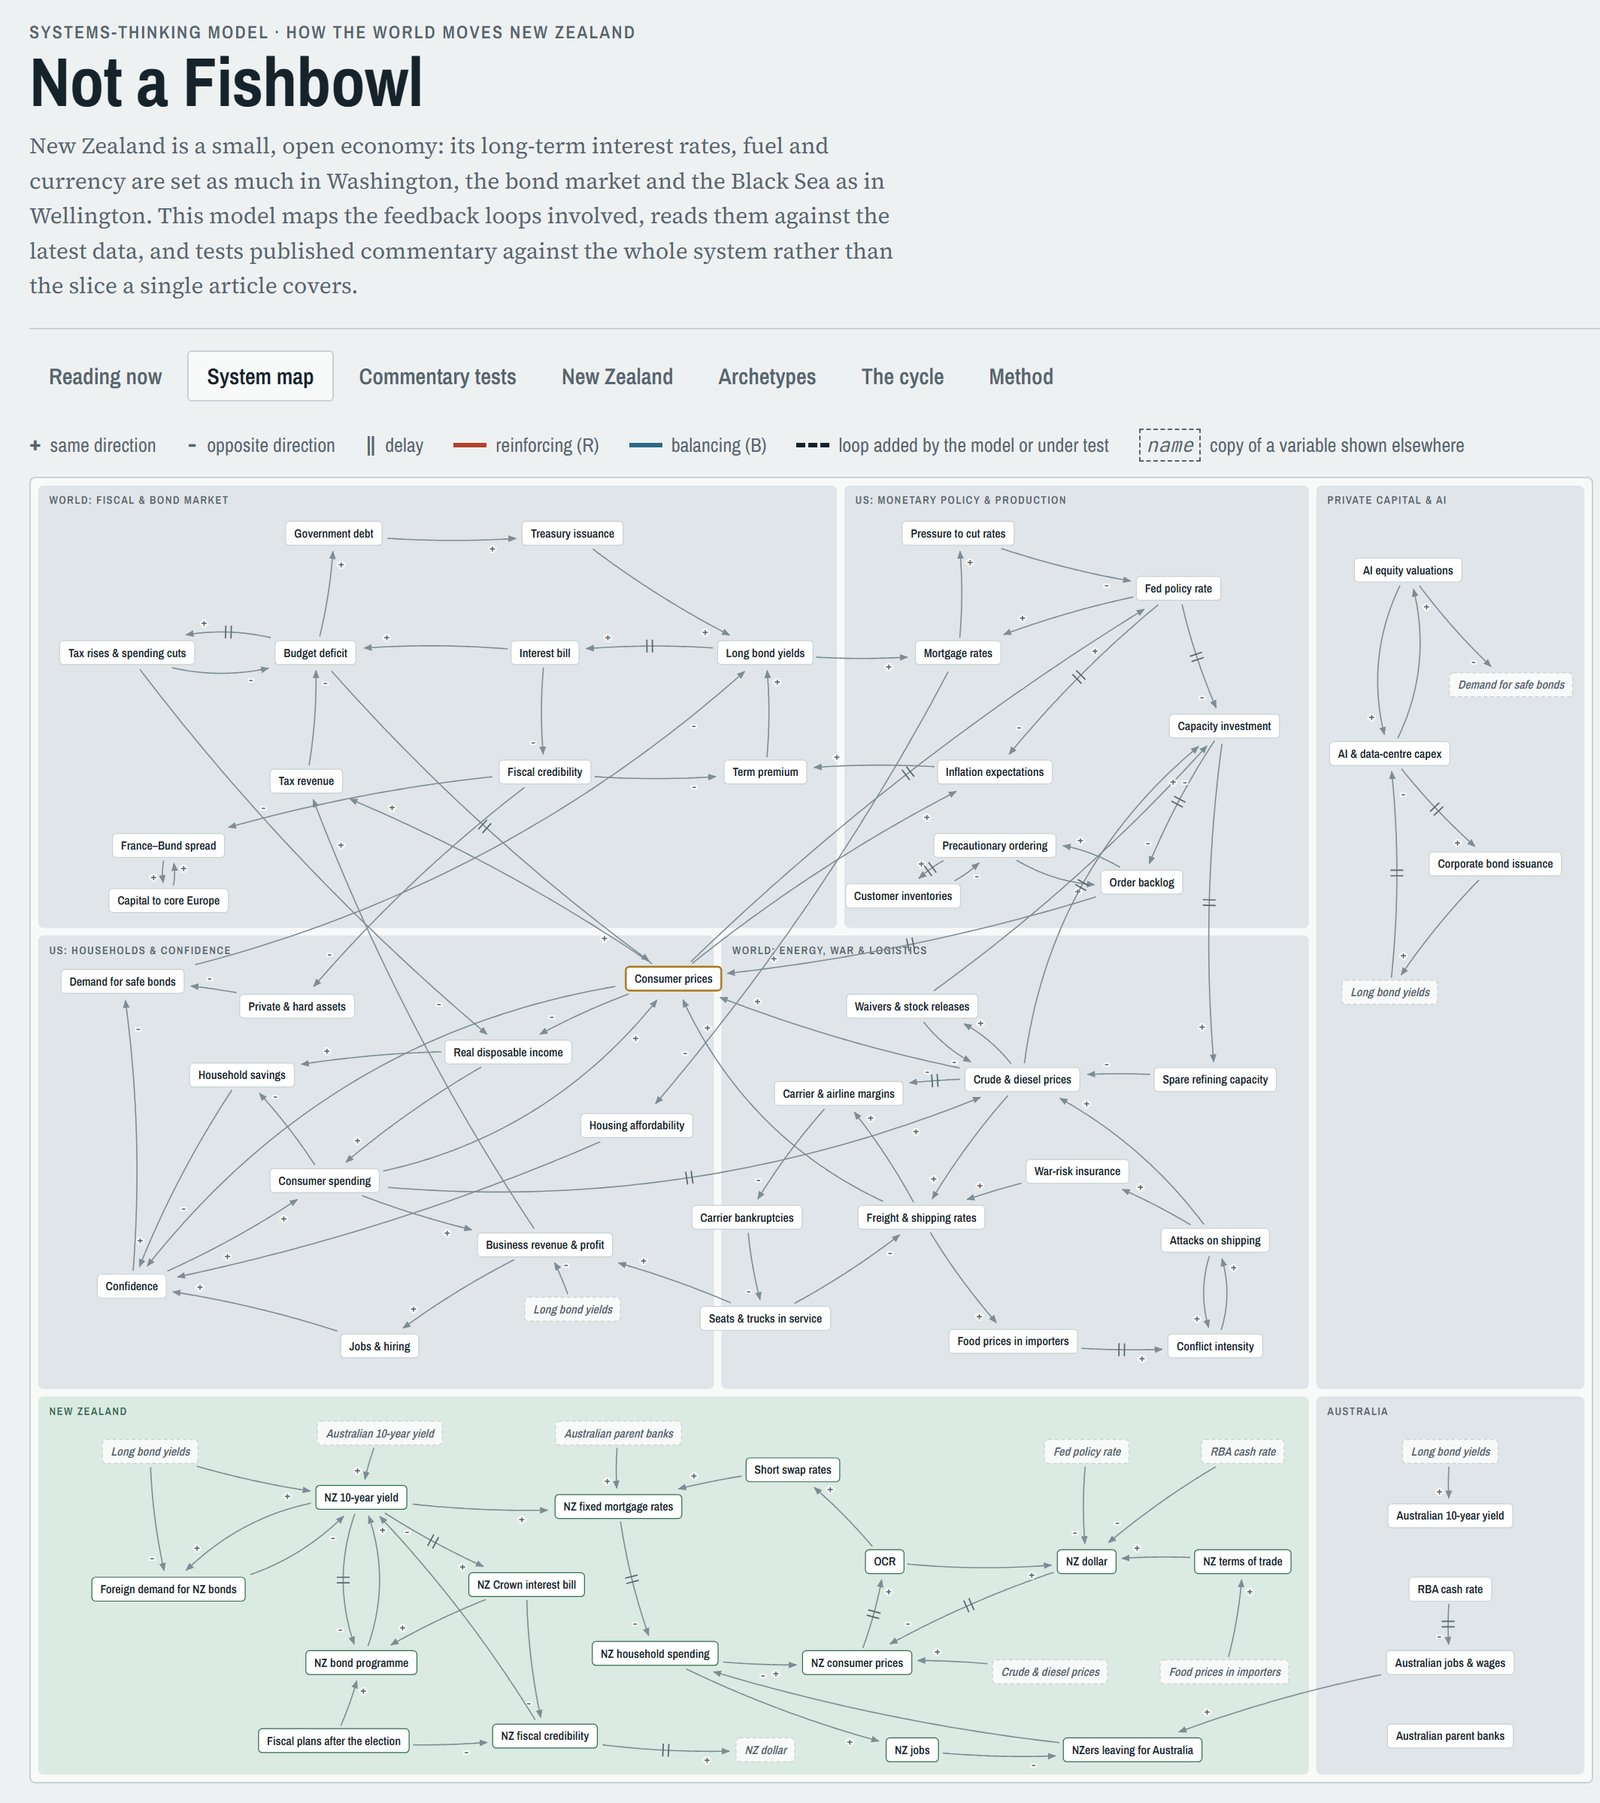
    So I built a model. It started for my own use, and it’s now a page on this site: Not a Fishbowl, at strategickata.com/systems. It maps how the world economy moves New Zealand through 34 reinforcing and balancing loops, across seven sectors: world bond markets, US monetary policy, US households, energy and war, private capital and AI spending, Australia, and New Zealand itself. Australia is the second channel after the US: its bond market, its central bank, the parent banks behind most New Zealand lending, and the jobs that draw New Zealanders across the Tasman. Live data drives each loop’s status, gaining, mixed, steady or fading, and where I don’t yet have an indicator for a loop, the page says “no indicator” and leaves it there.

    The part I care most about is the test log. When a piece of economic commentary is published, I run it through the model and ask the same questions every time. Which loops does it use? Which relevant loops does it leave out, and why do they matter? Does it rely on anything the model doesn’t hold? Does it stop at New Zealand’s border? What does it predict, even if only implicitly, and which indicator will show whether that holds? Each test gets a review date, and when the date comes it gets scored: held, partly, failed, or void if the event it depended on never happened. Nothing is deleted. The scorecard, misses included, is the record. A test judges the scope of the argument and the loops it covers, and leaves the author’s motive alone.

    The first commentary I tested was my own. I’d written a note on how US Treasury yields reach New Zealand, and I was confident in it. Run against the model, it came back partial. The long end of our rates is imported, as I’d said, but I’d written nothing about the short end, where most New Zealand mortgages price and where the RBNZ has real control. That’s the kind of blind spot I built it to find, and it found mine first.

    The first test on the live page is Roger J Kerr’s five indicators for the New Zealand dollar, from interest.co.nz. It’s there because its scope is system-wide: it crosses the border through US rates, AI borrowing, oil, and elections in both countries. Even so, the model found loops it didn’t use, including the offshore holders of NZ bonds who carry US moves into our rates.

    The page also carries an example of each of the other two scopes, so you can see the difference. David Skilling’s case that higher rates are a structural reset is partial: the argument is global, the data largely backs it, and it stops where the New Zealand question starts. Brian Easton’s check of the government’s fiscal record against Treasury’s 2023 forecast is narrow: careful on Treasury’s own numbers, but it measures debt as a share of GDP and leaves out the interest bill, which is the part that’s moving, mostly on rates set offshore.

    What you won’t see on the page are the party plans. During this election campaign I tested the fiscal and tax plans of every party that had published one, with the same template for all of them. Every one stopped at the border. They argued about Crown debt and the credibility premium New Zealand pays to borrow; as reported, none said what interest rates its debt track assumes, and all treated global shocks as something that might happen in future, when the cost is already flowing in through the bond market. That’s fishbowl analysis, from every side. I keep those as working notes for myself.

    Gold, then and now

    One loop in the model is my own hypothesis, and it’s under test like everything else. By the end of the Second World War, the United States held about two-thirds of the world’s monetary gold outside the Soviet bloc. Through both wars, money looking for safety went to America and into US government bonds, the quality asset of the day. Economists call it a flight to quality.

    I see similar triggers now, with a different destination. Money looking for safety seems to be moving away from government paper altogether and into private assets: shares, buildings, collectibles, corporate bonds, and gold, which was over US$4,100 an ounce on 13 October. If I’m right, that loop shows up in the data as gaining. If I’m wrong, the model will say so, and I’d rather find out there.

    The next four weeks

    The timing is a good test. Stats NZ publishes the September quarter CPI on 22 October. The RBNZ reviews the OCR on 28 October. The US midterms are on 3 November, the September quarter unemployment figures come out on 4 November, and New Zealand votes on 7 November. After that comes the new government’s fiscal plan, and Budget 2027, whoever wins.

    I’ll keep feeding the model commentary as these land, from New Zealand, the US and further afield. The readings are refreshed every week, so you can come back and see what moved, which tests held and which failed. If it turns out to be useful to someone besides me, maybe it becomes a small public service one day. For now it’s a sense-maker for me, and it will get better as more data goes in and more connections show up.

    I know there will never be a perfect model. If I can get 80 to 90% of the understanding of a situation by putting commentary through it, I think half the battle is won, maybe two-thirds of it. Whether any reading plays out depends on action or inaction, more often inaction, and even inaction here can be set off by decisions made somewhere else.

    1997 taught me a few things I still use. Don’t follow the crowd. Set your own goals and targets. Don’t be greedy. There’s always a root cause behind market behaviour and its triggers, and it’s rarely inside one border. The more I read, the more I learn about how economics behaves in practice, and most of that I didn’t learn at university.

    New Zealand is not a fishbowl. Neither was Malaysia in 1997.
  • The Hallucination You Can’t See

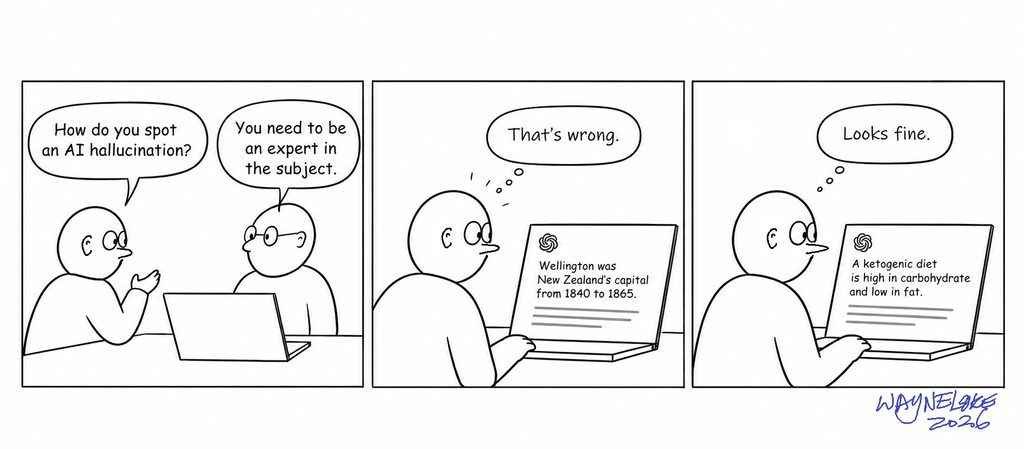
    After I published Knowledge Is Cheap Now, Murray MacRae PhD asked me on LinkedIn how you identify an AI hallucination. My answer was quick, and I still think it was right: if you’re an expert in the subject you can see it, and if you’re not, you mostly can’t. His question stayed with me, and in the weeks that followed I ended up on both ends of it, and the uncomfortable end was the one where I didn’t see it at all.

    The first time ran the other way round. On 9 September I was running an audit of the files that hold my writing system, 5 phases, one Claude model doing the evaluation and another carrying out the changes, and one finding said the Te Pūkenga restructure that ended my last role had been invented. It beat itself up about it, stating that my redundancy and my early retirement in November 2024 had been fabricated and hallucinated, and should come out. It only backed down when it went back to The Coach Said Ageism is a Myth, where I wrote about that restructure in June, and found the context it had been missing. I was made redundant. I retired early. I was there. Nobody else reading that audit would have known which way round the truth ran; I knew because it’s my life, and there’s no one more expert in it than me.

    Consistent, and wrong

    That audit checked my writing against what it had in front of it, and what it had in front of it was partial. I don’t write my Strategic Kata pieces in chronological order, some run ahead of when they happened and some reach back years, and the system that helps me edit holds its own selective memory of my career. Against that partial record, a restructure it couldn’t place looked invented. Internally consistent, externally wrong, and delivered with complete confidence.

    OpenAI’s researchers published a paper in September 2025 on why language models hallucinate,1 and their explanation is plainer than I expected. The models are trained and scored like students sitting a multiple-choice exam. If a model doesn’t know someone’s birthday, a guess has a 1 in 365 chance of being right, while “I don’t know” scores zero every time, so over thousands of questions the model that guesses looks better on the scoreboard than the one that admits it isn’t sure. So it guesses, and it guesses fluently. The way I read it, hallucination will always be there when the model hasn’t got the right context. I’m seeing less of it in my own work than when I started with AI a couple of years ago, and I’m not saying it’s gone, because September gave me three of them.

    Some hallucinations you can see from across the room. When I trained Gemini to draw my comics, it kept giving mouths to characters who don’t have mouths. Anyone could spot that. The ones that cost you are written in well-formed, confident sentences about something you don’t know well enough to argue with, and that’s where Murray’s question bites.

    Where I could see it

    On my own ground I catch it, and I was catching the human version of it long before AI arrived. At IRD, BNZ and Stats NZ nearly everything ran on Microsoft, and I read the vendor reports, the release notes and the updates because that was part of the job. When a supplier brought in a product person from headquarters, flown in from Europe or Australia or the US to present the new release, they tended to assume the room knew less than they did. Often the room knew more. Some of my team had been running the beta for weeks because they loved to tinker, and they knew what the product actually did, so every now and then what the presenter claimed didn’t match what we had seen with our own hands. The presenter believed every word, and was fluent about a product they hadn’t used the way we had.

    At ABN AMRO, when we moved into a new building, the data centre went into office space on the top three floors, and the project manager handed me the specification for the floor where the AS/400 and the other servers would sit. There was no raised floor in it. It had simply been left out, with no budget argument or short cut behind it. A raised floor is where the cooling air moves, where the power cables, data cables and ventilation run safely out of the way, and where the engineers get at all of it for maintenance, even on an office floor. I only saw what was missing because before ABN AMRO I had run a data centre at a local bank, in a different role. The raised floor went in, after some objection and a few rounds of discussion with leadership and finance. The specification had been wrong by omission, the same way AI can be: incomplete, with nothing on the page to tell you something is missing.

    A couple of years ago I asked ChatGPT to help revise my CV. It inflated my percentages, it translated my New Zealand job titles into what they would mean in the US, and it turned work that was done locally, and done well, into global impact. I laughed at it, because it’s a very good wordsmith with a strong sense of marketing. I have never sent that CV to anyone. I couldn’t stand behind evidence it had made up.

    On my own ground I can even see what I don’t know. In September, while I was drafting Does the Exit Interview Work? about our body corporate changing managers, Claude wrote that the outgoing manager ran 40 other buildings, and presented it as fact. I had no idea how many buildings they ran. It wasn’t my business, and they never told us. That’s how I knew the number was made up: I never had one to give, and nothing in the material said it. It came out before the piece went live.

    Three-panel comic. One bald character asks another, "How do you spot an AI hallucination?" and is told, "You need to be an expert in the subject." At a laptop, the character reads an AI answer saying Wellington was New Zealand's capital from 1840 to 1865 and thinks, "That's wrong." Then they read an AI answer saying a ketogenic diet is high in carbohydrate and low in fat, and think, "Looks fine."

    Where I couldn’t

    Now the other half. The same article had a second one in it, and that one I didn’t see. The evidence in it was a 2016 Harvard Business Review study by Everett Spain and Boris Groysberg.2 Claude compressed the study’s method into “188 executives across 210 organisations”, which can’t be right, since you can’t spread 188 people across 210 organisations. They had surveyed 188 executives and interviewed 32 senior leaders, who between them represented 210. The draft also left out where the authors land: exit interviews can work if a second-line manager runs them. I knew that. I had said the same about the concept in my first blog post on exit interviews in 2022, and I part company with them only because in practice I have never seen one work. Claude reported the citation as verified. I read it, and I published it.

    The next day a reader who knew the study wrote to me privately and told me it was wrong, twice. The correction sits at the foot of that piece, dated 24 September. I had read and scanned the study, and I never checked whether the numbers on my own page added up. The reader knew the study well enough to see they couldn’t. On that paper, I was the non-expert.

    Big firms miss it too. Australia’s Department of Employment and Workplace Relations paid Deloitte AU$440,000 for a 237-page review of its welfare compliance system.3 The report cited academic work that doesn’t exist and a quote from a Federal Court judgment that isn’t in the judgment. Deloitte had used GPT-4o to help draft parts of it. A firm full of professionals put its name on it. Chris Rudge, a University of Sydney researcher in health and welfare law, read it and saw the problem, because he knew the literature it was citing. Deloitte refunded the final instalment of the contract in October 2025.

    Closer to home, in February this year the New Zealand Supreme Court dealt with an applicant representing himself in a Family Court matter. His submissions cited cases that looked real: real case names, attached to citations that pointed somewhere else. The court said they appeared to have been hallucinated by an AI application,4 and warned that relying on false citations, including unverified AI output, may in serious cases amount to obstruction of justice or contempt of court. He had no lawyer, and little chance of seeing it, and the warning landed on him anyway.

    What a non-expert can do

    Back to Murray’s question. My first instinct, when I dictated the draft of this piece, was that a non-expert could paste the paragraph back into AI and ask whether it holds up. I have talked myself out of that. It’s like asking the con artist to tell you he’s honest, and if you can’t judge the original, you can’t judge the verdict either. It will catch some things, a dead link, a case that doesn’t exist at all. It’s much less reliable on a real study with its method bent out of shape, which is exactly the kind that got past me.

    What caught all three was a person who knew the original well. My reader knew Spain and Groysberg’s numbers. Chris Rudge knew the work Deloitte claimed to be citing. The Supreme Court had the law reports. So this is what I do now when I’m outside my own ground. I open the source myself, the actual paper or judgment or release note the summary was made from, and check that the sentence carrying the weight says what I’ve been told it says. And when it matters, I borrow an expert, someone who has walked that ground, and ask them to read it before I rely on it.

    Niklas Gruhn wrote a blog post in August about the meat proxy,5 the person who forwards whatever the AI produced without reading it, understanding it or checking it. The burden of verification sits with whoever puts their name on the output, and for Strategic Kata that’s me. My process already had checks in it: the Wispr Flow voice draft, the excavation, the back and forth, an audit against what I’ve published before and what’s online. It still let one through. So every citation now gets two rounds before it goes out: I open the link to see that it lands where it says it does, and I search the source for the passage I’m leaning on and read it there. It’s a quick read. It’s also the price of my name on the page.

    Murray was right. I just didn’t expect the non-expert to be me.


    1. Adam Tauman Kalai, Ofir Nachum, Santosh S. Vempala and Edwin Zhang, Why Language Models Hallucinate, OpenAI, September 2025: https://arxiv.org/abs/2509.04664 ↩︎
    2. Everett Spain and Boris Groysberg, “Making Exit Interviews Count”, Harvard Business Review, April 2016: https://hbr.org/2016/04/making-exit-interviews-count ↩︎
    3. “Deloitte to partially refund Australian government for report with apparent AI-generated errors”, Associated Press via Fortune, 7 October 2025: https://fortune.com/2025/10/07/deloitte-ai-australia-government-report-hallucinations-technology-290000-refund ↩︎
    4. Jones v Family Court at Whangārei [2026] NZSC 1, 11 February 2026, at [7]: https://www.courtsofnz.govt.nz/assets/cases/2026/2026-NZSC-1.pdf ↩︎
    5. Niklas Gruhn, blog post on the meat proxy, 3 August 2026: https://gruhn.me/blog/2026-08-03/ ↩︎
  • Two Ledgers

    I used to tell my teams a story from Star Trek. An officer walks up to the captain of the Enterprise and asks permission to leave the ship, to be beamed across to another starship or out to a station somewhere, because that’s where the next step in their career is waiting, and the captain agrees and wishes them well. Nobody stays on the ship forever. People come and go in any organisation; some stay until the day they retire, many more move through three or four in a working life, and I told the story so that nobody in the room felt disloyal for wanting to leave, and nobody felt abandoned when a colleague did.

    What I never pointed out, because it never occurred to me, is that the officer asked.

    This month my LinkedIn feed started filling up with posts from people in my network at ANZ, my old employer. Their positions have been disestablished, and they are in the holding period now, waiting to find out whether they can reapply for a role or will be made redundant. None of them asked to be beamed anywhere. The public version came out last week: ANZ New Zealand is proposing more than 100 redundancies in its technology team, with more than 400 roles affected, as it consolidates software testing under a single partner and considers moving that work offshore to India and the Philippines. The roles named include quality assurance engineers, lead engineers, product owners and project managers. It sits inside a group-wide programme to cut 3,500 jobs by September 2026, which the Chief Executive has described as simplifying the bank.

    I feel for them, and it landed harder than the usual restructure headline because I’ve done the same thing at the same bank, sent the same kind of work to the same country, and back then nobody lost their job.

    The same move, 18 years earlier

    Between 2007 and 2009 I was the Manager for Consumer Finance Development at ANZ, and one job that came round like clockwork was Scheme Compliance. Every 6 months Visa and Mastercard revise their requirements, for security and for improvements, and every card issuer has to change its systems to match. We had to do it twice, because the bank still ran two credit card systems, National Bank’s and ANZ’s, one on Systematics and the other on Tandem with Base24. Most of the effort went into testing, and the people who could do the work were hard to find. Recruiting COBOL, Tandem and mainframe people in New Zealand was difficult then, so we relied on the old hands, the ones who had been in the organisation long enough to know every corner of both systems.

    Then an idea got floated. ANZ had a growing pool of developers and testers in Bengaluru, so what if we sent the Scheme Compliance work to them? That’s what we did. We brought their developers and testers over to New Zealand and trained them on what had to be done, and we sent one of our own, the Systematics Chief Analyst Programmer, to Bengaluru to oversee the work and keep training on the ground. It was our first go at running a remote development team. The time difference was 6.5 hours, or 7.5 depending on daylight saving, and once we found the rhythm it felt like running an IT shop 16 hours a day: meetings early in the morning or late in the afternoon before we closed, work handed over at the end of our day, and results waiting for us the next morning.

    We didn’t disestablish a single programmer, tester or analyst in Wellington. To us it was one technology team working from two places. To technology leadership it was a large saving, more output for the same cost, and my records put it at about $400,000 a year in development cost. The bigger effect was on the local team, who were freed from the 6-monthly compliance grind and moved onto product enhancements and new products, which was more meaningful work for them and more useful to the bank.

    So the same bank has sent the same kind of work in the same direction twice. The first time, the local team moved on to better work. This time, more than 100 people are waiting to hear whether they still have a job.

    Two books

    Looking back, I’ve asked myself whether we kept two books in those years, and I’m not sure we did. I guess every manager keeps a first book, the people who produce and do the work. In harder times a second one appears, the list of people you aren’t so sure of. When things are going well the two books are the same book; there is more work than people, everyone is needed, and nobody has a reason to open the second. When the economy tightens, and when organisations bring in stack ranking (I wrote about how that works in The Merry-Go-Round), the second book separates from the first, and managers keep it handy, because the day a reorganisation arrives they will be asked for names at short notice and the second book is where the names come from.

    The second book records who is dispensable, and salary has surprisingly little to do with it. In 2008 the most expensive people in my area were the old hands on Systematics and Tandem, and they were the least dispensable people in the building, because hardly anyone else in the country could do what they did. The market had written their entry in the first book for us.

    This is what makes the second book so hard to argue with: neither book is lying. The first records something true, that this person does good work and the team relies on them. The second also records something true, that the organisation could get this work done without this person, cheaper, somewhere else, or not at all. Both can describe the same person on the same day. Nothing in ANZ’s announcement says the testing was bad; the reasons given are a cheaper place for the work to go and a cost target to meet. When an organisation is short of people, the capacity freed by sending work away goes straight into the next piece of work, which is what happened to my team in 2008, and the two books stay together. When it’s short of money, the freed capacity is the saving, and the books split.

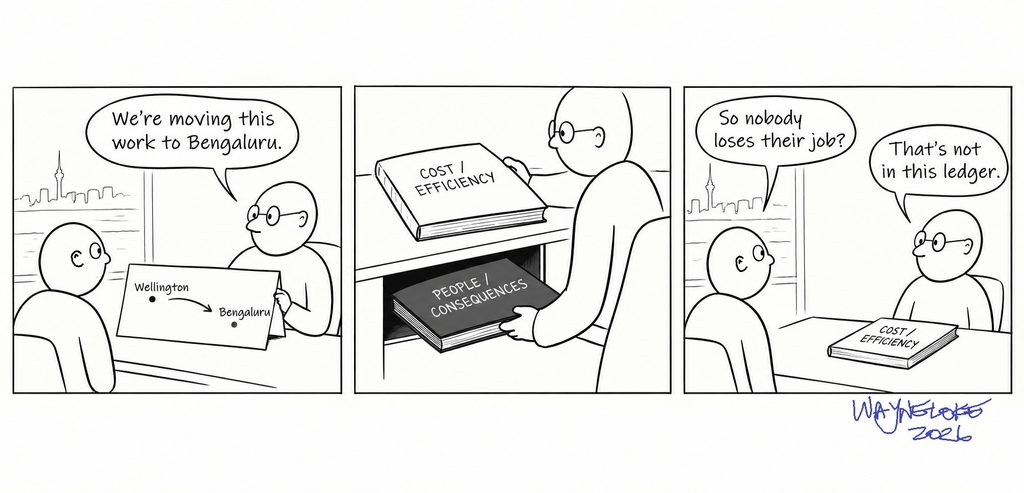
    A comic strip of two people discussing work going to Bengaluru. There's two books - one on people and the other on cost. The one on cost doesn't mention if people loses their job.

    The second book is an estimate, though, and sometimes a poor one. In The Redistribution Reflex I wrote about people ANZ made redundant who came back as contractors, sometimes within months and usually at a higher rate, because the knowledge they carried couldn’t be replaced. The first book had been right all along. It just wasn’t the one being read that day.

    My name in someone else’s book

    If I kept two books as a manager, then someone kept two books with my name in them. Whether you land in the first or the second comes down to whether you’re dispensable or indispensable, and I guess even the indispensable eventually run out of justification. At Te Pūkenga that was literal. The government had already signalled it was disestablishing the whole organisation, and when the organisation itself comes off the government’s books, every person in it goes with it, however useful they are.

    When Microsoft retired Whiteboard this year, the app was still useful to me and no longer worth it to Microsoft, and I wrote in The Whiteboard I Love is Being Retired that I’d lived a larger version of the same thing when my role ended in November 2024. I had a good plan, I was ready for retirement, and I still got shoved out unexpectedly. There was no bitterness, and there still isn’t. What I didn’t expect is how long it took to get used to the idea of being exited on someone else’s terms. I guess you have to live through it to know you come out intact.

    The playing field

    None of this needs a villain. Years ago I read two books that shaped my thinking more than I realised at the time. Kenichi Ohmae’s The Borderless World, published in 1990, argued that national borders were mattering less and less to how companies compete. Thomas Friedman’s The World Is Flat, in 2005, opens with Friedman on the Infosys campus outside Bangalore, as it was called then, where Nandan Nilekani told him “the playing field is being leveled.” In 2008 I was on the comfortable side of that playing field; we sent the work, kept our people and banked the saving. In 2026 my old colleagues in Wellington are on the other side of it. As long as work can move across borders there will always be a cheaper place to do it, and under the economic pressure most organisations are carrying now, it’s a race to the bottom that nobody in particular is running.

    So what can anyone do about which book they’re in? In May I wrote The Four Unwritten Rules That Keep You Employed: be visible, be easy, be useful, be ready. I still think they’re right, and they will keep you in the first book for longer. They won’t close the second book, because the second book gets written about the work and its price, whoever happens to be doing it. You won’t know when your time runs out, and the only protection I know is a plan B in hand before you need it, so that when shit happens you’re still intact and moving on your own terms.

    Which takes me back to the Enterprise. The officers in my story got to ask. A plan B is what lets you be the one who asks.

    Always be prepared.

  • Does the Exit Interview Work?

    Does the Exit Interview Work?

    Two contractors turned up at the same fire alarm fault on the same morning, one sent by the company we were leaving, one sent by the company we had just moved to. Neither knew the other was coming. That is how the committee found out that the cancellation instruction we had given in writing, weeks earlier, had never been executed.

    Nobody told us. No handover note flagged it. We discovered it because two people arrived at the same address for the same fault and looked at each other.

    Three months before that morning, I had sat through an exit interview.

    I chair a body corporate committee in Wellington, and we had given our management company 90 days’ notice. The operations manager asked for a meeting to understand why we were leaving and what the company could do better. It was a courteous conversation. They took notes, they thanked me for being direct, and they said the feedback would go to the owner. They also said, in the politest possible way, that we would regret it. The market would show us what good service actually costs, and they intended to use the notice period to prove the company had changed.

    So I had 90 days to watch that claim get tested. That is a longer measurement window than any interview, and a harder one to fake, because it is the one stretch of time where a supplier has every incentive to perform and no commercial reason left to bother.

    Long story short, I saw no improvement. It got worse. Invoices went unpaid. Follow-ups stopped. The transition itself was the worst part: the incoming provider came back to us with a list of missing documents and gaps in the records, the service address for the building was still registered to the outgoing company, contracts we had instructed them to cancel were still running, and nothing had been forwarded on. We had grounds to seek compensation. We decided chasing it would cost us more time than fixing the mess ourselves, so we fixed the mess ourselves.

    Every promise made in that room was meant, I think. The operations manager simply had no mechanism to deliver any of it.

    The version of this I wrote in 2022

    I first wrote about exit interviews in October 2022, on a blog called Small Simple Steps. That blog has since closed, and its readers were pointed here. I haven’t migrated the old posts, and I don’t intend to migrate them as they were, because most of them were written by someone who still had an employer and still wrote like it. This one is worth reopening with more context behind it, because I have now been on both sides of the same ritual.

    The 2022 version was about employees. Someone resigns, HR schedules a 45-minute conversation in their final week, and asks what could have been done differently. My friends, asked in private, told me it was a waste of time for three separate reasons: they knew nothing would be implemented, they didn’t want to say out loud that their manager was the problem, and they didn’t want to burn a bridge they might need. I concluded then that the concept was sound and the execution was poor, and that regular one-on-ones were the better instrument.

    I’d now put it harder. The problem sits in the design.

    Where the feedback goes

    In 2012 and 2013, Everett Spain and Boris Groysberg surveyed 188 executives and interviewed 32 senior leaders, who between them represented 210 organisations in 33 industries, and published the findings in Harvard Business Review in 2016. About 75% of those companies ran exit interviews in some form, and 71% of them handed the process to HR. Spain and Groysberg think the instrument can be made to work, and their fix is to have a second-line manager run the interview, someone far enough from the day-to-day to hear the real thing and senior enough to act on it. Their own number puts the job with HR in 71% of those organisations. HR is the one function that can’t act on what it hears without exposing who said it.

    HR runs it because HR is neutral, and neutrality is what makes the departing person willing to speak. The same confidentiality that makes someone willing to say the real thing also makes what they say unusable. The specific complaint, the one that names a manager and a pattern and a date, is exactly the part that cannot be passed on without identifying who said it. So it gets aggregated, anonymised, softened, and summarised into a quarterly theme like “career development opportunities.” Across banks, a tax department, a statistics agency, and two tertiary institutions, I have never once seen a manager receive the substance of what a departing team member said about them. Ask your own manager whether they have ever been shown one.

    And suppose it did reach them. A line manager holds very little of the machinery that makes people leave. They don’t set the salary bands, they don’t set the promotion criteria, they don’t control headcount, and they don’t own the restructure timetable. Even training, the smallest and most obvious thing a departing person asks for, runs on financial delegation: budget ownership generally starts at senior manager and above, so if you hold no budget and no financial delegation, and most line managers hold neither, you write a training proposal and send it up to your own manager to spend the department’s money, and in some organisations HR co-approves it on top of that. Handing that person a well-argued piece of exit feedback is like handing someone a detailed engineering report on a data centre they don’t own.

    There is your one analogy for the piece. I’ll keep the rest literal.

    The promise made to the people who stay

    This is the part I didn’t see clearly in 2022.

    The exit interview carries a second message, and its audience is everyone still in the room. It says: we collect feedback, we take it seriously, and things will get better. It’s the same promise the operations manager made to me, delivered with the same sincerity, backed by the same absence of machinery.

    Watch what happens after a wave of resignations in any organisation you’ve worked in. Exit interviews are conducted. An engagement survey follows. A working group forms. Twelve months later, the people who stayed have watched the identical conditions produce the identical outcome, and they’ve learned something the organisation never intended to teach them: that saying the true thing out loud changes nothing, and the safe play is to stop saying it. High turnover alongside diligent exit interviewing is a company that has industrialised the appearance of working on its problems.

    You were never their kind of customer

    Here’s the uncomfortable half.

    Organisations are calibrated for a particular kind of employee and a particular kind of customer: the one who fits the existing process, doesn’t escalate, doesn’t ask for exceptions, and doesn’t make anybody rewrite anything. That person is cheap to serve and easy to manage, and by the organisation’s own measures they are a good employee and a good client. If you are the one sitting in an exit interview with substantive feedback, you have already demonstrated that you are not that person.

    Which means the simplest reading of my 90 days is that the management company was letting us go, and the exit interview was the polite form of the goodbye. The feedback probably did reach the owner. The owner probably read it and concluded that a body corporate committee with an engaged chair who checks invoices and follows up cancellations is more trouble per dollar than the other buildings on the books that never ring. That is a rational commercial judgement. It just isn’t the one the meeting pretended to be about.

    This is why most businesses are average. Not failing, not good, average. Average is an equilibrium; businesses settle there and stay. The organisations we read about in the business books are a rounding error, and even they don’t hold it. Nike spent nearly 18 years in the S&P 100 and came out of it on 21 September 2026, with its market capitalisation down from roughly $264 billion to about $57 billion, a fall of around 78%, and revenue down 10% to $46.3 billion in the 2025 financial year. Nobody stays great. Mostly, nobody even tries for very long, because average is comfortable and it pays the bills.

    What’s actually left

    I’m not going to tell you to give better exit feedback. The instrument doesn’t work, the person receiving it can’t act, and by the time you’re in the chair you’ve already been reclassified as somebody’s acceptable loss.

    But the last line of my own thinking on this hasn’t changed, and it’s the one that matters: improvement doesn’t require a policy change or a budget. Almost everything a manager can do for the people in front of them is free. A one-on-one that is never cancelled. Thirty minutes that isn’t a status update. Asking what someone wants in three years and then remembering the answer. Telling your own manager, in writing, what your team told you, while they’re all still employed. None of that needs sign-off, and all of it happens inside the autonomy a line manager already has.

    Be clear about the limits of it. That fixes your team. It will not fix the organisation, and you should stop expecting the organisation to be fixable by anyone at your level. Do it anyway, because the people in front of you are real and the organisation is an abstraction.

    As for the feedback itself, I’ve learned the timing from both chairs. On the committee, I now say the difficult thing to a supplier while the contract still has years to run and my opinion is still worth something to them. As an employee, I should have said it in month four rather than in the exit interview.

    I say it while I’m still the customer.


    Correction, 24 September 2026: the paragraph on Spain and Groysberg’s research has been corrected. The first version said they surveyed 188 executives across 210 organisations; they surveyed 188 executives and interviewed 32 senior leaders, who together represented 210 organisations. It also left out that the authors conclude exit interviews can work when a second-line manager runs them. Thank you to the reader who pointed this out.